

One lawsuit, one kitchen fire, or one burst pipe can undo years of hard work. Most owners know this, yet many still run their companies with coverage they bought quickly and never reviewed.
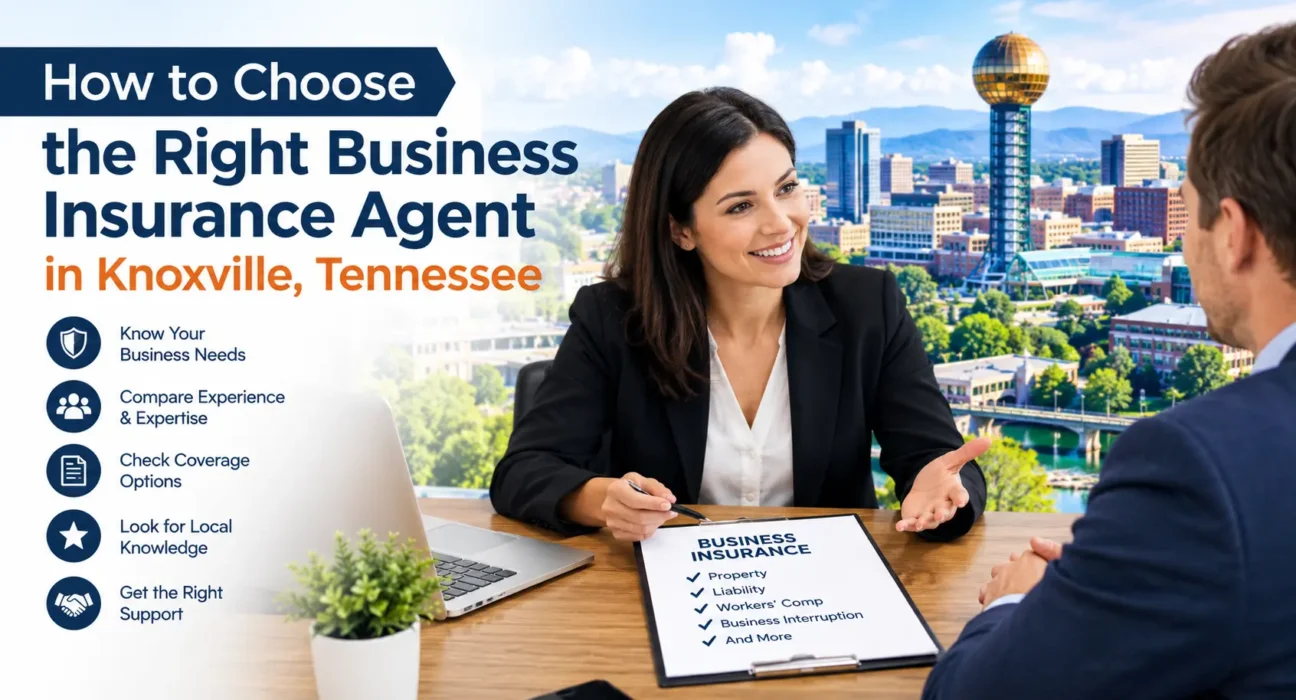
If you run a business in East Tennessee, a trusted business insurance agent in Knoxville Tennessee can be the difference between a bad week and a business-ending loss. This guide explains what an agent does, which coverage types matter most, and how to pick the right professional for your company.
Why Knoxville Businesses Need the Right Insurance Partner
Knoxville’s economy is a healthy mix of small retail shops, restaurants, contractors, healthcare practices, tech startups, and tourism-related companies. Its position near the Great Smoky Mountains and the University of Tennessee brings steady foot traffic, events, and seasonal swings.
That variety creates real risks:
- Storm and flood damage from East Tennessee weather
- Customer injuries at busy retail and restaurant locations
- Vehicle accidents for delivery and service companies
- Data breaches at businesses that store customer information
- Employee injuries on job sites and in warehouses
A local agent understands these conditions. A generic online quote form usually doesn’t.
What Does a Business Insurance Agent Actually Do?
An agent helps you understand your risks, compare policies, and buy coverage that fits. After the sale, a good one stays involved.
In practice, that means they:
- Review your operations, property, and payroll
- Identify gaps in your current coverage
- Compare quotes from multiple insurance carriers
- Explain policy language, limits, and exclusions in plain terms
- Help you file claims and follow up with the carrier
- Update your coverage as your business grows
Independent Agent vs. Captive Agent
This distinction matters when you are comparing options.
Independent agents work with several insurance companies. They can shop your policy across the market, which often gives you more choices on price and coverage.
Captive agents represent one company. They know that company’s products well, but they can only offer what it sells.
Neither type is automatically better. Still, many Knoxville business owners prefer independent agents for the flexibility.
Types of Business Insurance Coverage to Know
You don’t need every policy on the market. Here are the ones most businesses in Tennessee should evaluate.
General Liability Insurance
General liability insurance is common insurance coverage for many small businesses. It may protect against claims for third-party bodily injury, property damage and some advertising claims. For instance, when a customer slips and injures themselves on your business property, the policy might be used to help settle the eligible medical costs, legal fees and related claims.
Commercial Property Insurance
It protects your building, equipment, inventory, and furniture from fire, theft, vandalism, and certain weather events. Renters need it too, since your landlord’s policy doesn’t cover your belongings.
Workers’ Compensation Insurance
Tennessee generally requires employers with five or more employees to carry workers’ comp, and construction businesses face stricter rules. Requirements can change, so confirm current rules with your agent or the Tennessee Department of Labor and Workforce Development.
Business Owner’s Policy (BOP)
A Business Owner’s Policy (BOP) combines general liability and commercial property insurance into one package, often at a lower cost than purchasing the coverages separately. It can be a practical option for many small and mid-sized businesses seeking convenient, broad protection.
Commercial Auto Insurance
The insured coverage area in commercial auto insurance will also include vehicles used for business activities, accidents, property damage, and liability claims, depending on the policy. Commercial coverage can help protect your business from the unexpected costs associated with it because some of the coverage in personal auto insurance policies may be excluded for business use.
Professional Liability (Errors & Omissions)
Consultants, accountants, designers, and healthcare providers rely on this to cover claims of negligence or mistakes in their services.
Cyber Liability Insurance
Even a small shop that takes card payments can suffer a breach. This coverage helps with notification costs, legal fees, and recovery.
How to Choose a Business Insurance Agent in Knoxville Tennessee
Picking an agent is a bit like hiring an employee. Ask good questions before you commit.
1. Check Their License and Reputation
Agents must be licensed through the Tennessee Department of Commerce & Insurance. You can verify a license through the state’s website. Then read online reviews and ask other local owners who they use.
2. Look for Industry Experience
A restaurant owner and a roofing contractor face very different risks. Ask whether the agent has worked with businesses like yours.
3. Ask About Carrier Options
The more carriers an agent can access, the more likely you are to find strong coverage at a fair price.
4. Judge Their Communication
Do they explain things clearly, or bury you in jargon? A good agent answers questions without making you feel rushed.
5. Ask About Claims Support
Insurance proves its value when something goes wrong. Ask how they help clients during a claim and how quickly they respond.
Questions to Ask Before You Sign
Bring this short list to your first meeting:
- What risks do you see in my type of business?
- Are there coverage gaps in my current policy?
- What are the deductibles and limits, and why do you recommend them?
- Which discounts or bundling options might apply?
- How often will we review my policy?
The answers tell you whether the agent is giving advice or just selling.
Smart Ways to Lower Your Business Insurance Costs
Cheaper is not always better, but you can often reduce premiums without losing protection.
- Bundle policies through a BOP
- Raise deductibles if you have the cash reserves to cover them
- Improve safety practices and keep records of training
- Install security systems, fire alarms, and sprinklers
- Review coverage annually so you aren’t paying for outdated limits
- Maintain a clean claims history where possible
Your agent can tell you which of these will have the biggest effect for your industry.
Final Thoughts
Insurance isn’t the most exciting part of running a company, but it quietly protects everything else you’ve built. The right business insurance agent in Knoxville Tennessee will do more than hand you a quote. They’ll learn your business, point out risks you hadn’t considered, and stand beside you when a claim happens.
Take time to compare agents, ask direct questions, and review your coverage every year. For more practical guidance on running and growing your company, explore the resources at Top Business Magazine.
Frequently Asked Questions
How much does business insurance cost in Knoxville, TN?
Costs vary by industry, location, payroll, claims history, and coverage limits. A small low-risk office may pay far less than a contractor or restaurant. A local agent can give you an accurate quote after reviewing your operations.
Do I need a business insurance agent, or can I buy online?
You can buy online, but an agent offers personal advice, helps compare carriers, and assists with claims. This is especially useful if your business has complex or industry-specific risks.
Is workers’ compensation required in Tennessee?
Generally, yes, for employers with five or more employees, and stricter rules apply in construction. Confirm current requirements with your agent or the state labor department.
What is the difference between GL and BOP?
General liability insurance protects against third party bodily injury, property damage and other legal costs. A Business Owner’s Policy (BOP) is an owners’ policy that is a single policy offering general liability coverage and commercial property coverage bundled together at a more economical combined premium.
How often should I review my business insurance?
Review it at least once a year, and any time you hire staff, move locations, buy equipment, or add new services.